A first salary can either become the beginning of financial freedom or the foundation of years of financial pressure. If a newly employed teacher gets the first financial step wrong, correcting the course later becomes increasingly difficult. The habits formed around the first salary can quietly shape an entire teaching career—from borrowing and saving to family obligations, investment and retirement.
The lesson is simple: financial freedom is not created by earning more alone; it is created by deliberately managing what is earned.
Before spending the first salary, a teacher should establish the actual take-home amount after statutory deductions, loans and other commitments.
The first questions should be:
- How much is available after deductions?
- What must be paid every month?
- How much can safely be saved?
- What debts need attention?
- How much can reasonably go towards family support?
- What financial goals should be started immediately?
The first salary should therefore be treated as a financial planning tool, not a licence for immediate consumption.
Give every shilling a job
A practical planning framework for a teacher taking home KSh50,000 could look like this:
| Priority | Percentage | Amount (KSh) |
|---|---:|---:|
| Housing and utilities | 25% | 12,500 |
| Food and household needs | 20% | 10,000 |
| Transport | 10% | 5,000 |
| Emergency savings | 10% | 5,000 |
| Long-term investment/goals | 10% | 5,000 |
| Debt repayment | 8% | 4,000 |
| Family support | 7% | 3,500 |
| Professional development | 5% | 2,500 |
| Personal/social spending | 5% | 2,500 |
| **Total** | **100%** | **50,000** |
This is a planning framework rather than a universal formula. A teacher with unusually high rent, existing debt or family responsibilities should adjust the proportions without abandoning the principle of spending below income.
The important habit is to save and plan before discretionary spending, rather than saving whatever remains at the end of the month.
Build protection before pursuing wealth
Emergency savings should come before aggressive investment. A teacher can begin with the equivalent of one month of essential expenses and progressively build a reserve covering several months.
At the same time, consumer debt should be controlled. A loan should never be mistaken for additional income. Before borrowing, the teacher should consider the total repayment, interest and charges and whether the debt creates a productive benefit or merely finances consumption.
Put boundaries around generosity and lifestyle
New employment often brings pressure from relatives, friends and colleagues. Supporting family is important, but generosity without limits can undermine financial stability.
A defined family-support allocation makes generosity sustainable.
The same discipline should apply to lifestyle. A new teacher does not need an expensive phone, car, furniture or social lifestyle simply because a regular salary has arrived.
The first salary should improve financial security before it improves appearances.
Small recurring expenses also matter. Daily snacks, unnecessary trips, impulse purchases, entertainment and unplanned contributions can quietly consume money that could have built savings or reduced debt.
Invest in the teacher before investing heavily elsewhere
Professional development is itself an investment.
A teacher can use part of the income to strengthen professional, digital and financial skills, acquire useful resources or pursue training that improves competence and future earning capacity.
Investment decisions should then be approached carefully. Before committing substantial money, a teacher should understand the product, risks, charges, liquidity and obligations involved. Where the decision is complex or significant, qualified and appropriately regulated financial advice can complement personal financial literacy.
The first 30 days and the pathway to financial freedom
The first 30 days matter
The first month can establish the discipline for the years ahead.
Days 1–3: Study the payslip and establish actual income, deductions, debts and essential expenses.
Days 4–7: Create a realistic monthly budget and postpone major purchases.
Days 8–10: Automate or immediately set aside money for emergency savings and long-term goals.
Days 11–15: Establish a separate emergency reserve and begin building it progressively.
Days 16–20: Audit all debts and avoid unnecessary new borrowing.
Days 21–23: Set a sustainable limit for family and social obligations.
Days 24–26: Set short-, medium- and long-term goals, including professional development.
Days 27–28: Research any investment carefully before committing money.
Days 29–30: Review actual spending against the budget and correct the leaks before the next salary arrives.
If the first steps have already been missed
Missing the early steps does not make financial freedom impossible. It simply means that correcting the course may require greater discipline.
The teacher should start with a financial audit: determine where the money is going, eliminate avoidable expenditure, address expensive debt, rebuild emergency savings and establish a realistic long-term investment plan.
Technical financial advice can be particularly useful where debt restructuring, insurance, retirement planning or significant investments are involved. But professional advice should not replace personal understanding. The teacher should still know what they are buying, how much it costs and what risks they are accepting.
The financial freedom pathway
Financial discipline becomes easier when it follows a clear sequence:
Understand income → control expenditure → build emergency savings → manage debt → invest consistently → acquire productive assets → prepare for retirement.
The order matters. Trying to build wealth while continuously borrowing to finance consumption creates a fragile financial foundation.
A teacher who consistently directs even modest amounts towards savings, investment and professional growth can gradually turn a salary into financial security.
The real test of the first salary
The greatest danger facing a newly employed teacher is not necessarily a low salary. It is allowing the first salary to establish habits that become increasingly expensive to reverse.
If the first income is consumed by lifestyle, borrowing and unplanned obligations, every subsequent salary may arrive already committed.
But if the first salary establishes budgeting, saving, debt control, disciplined generosity, professional investment and long-term planning, each subsequent salary has a stronger foundation.
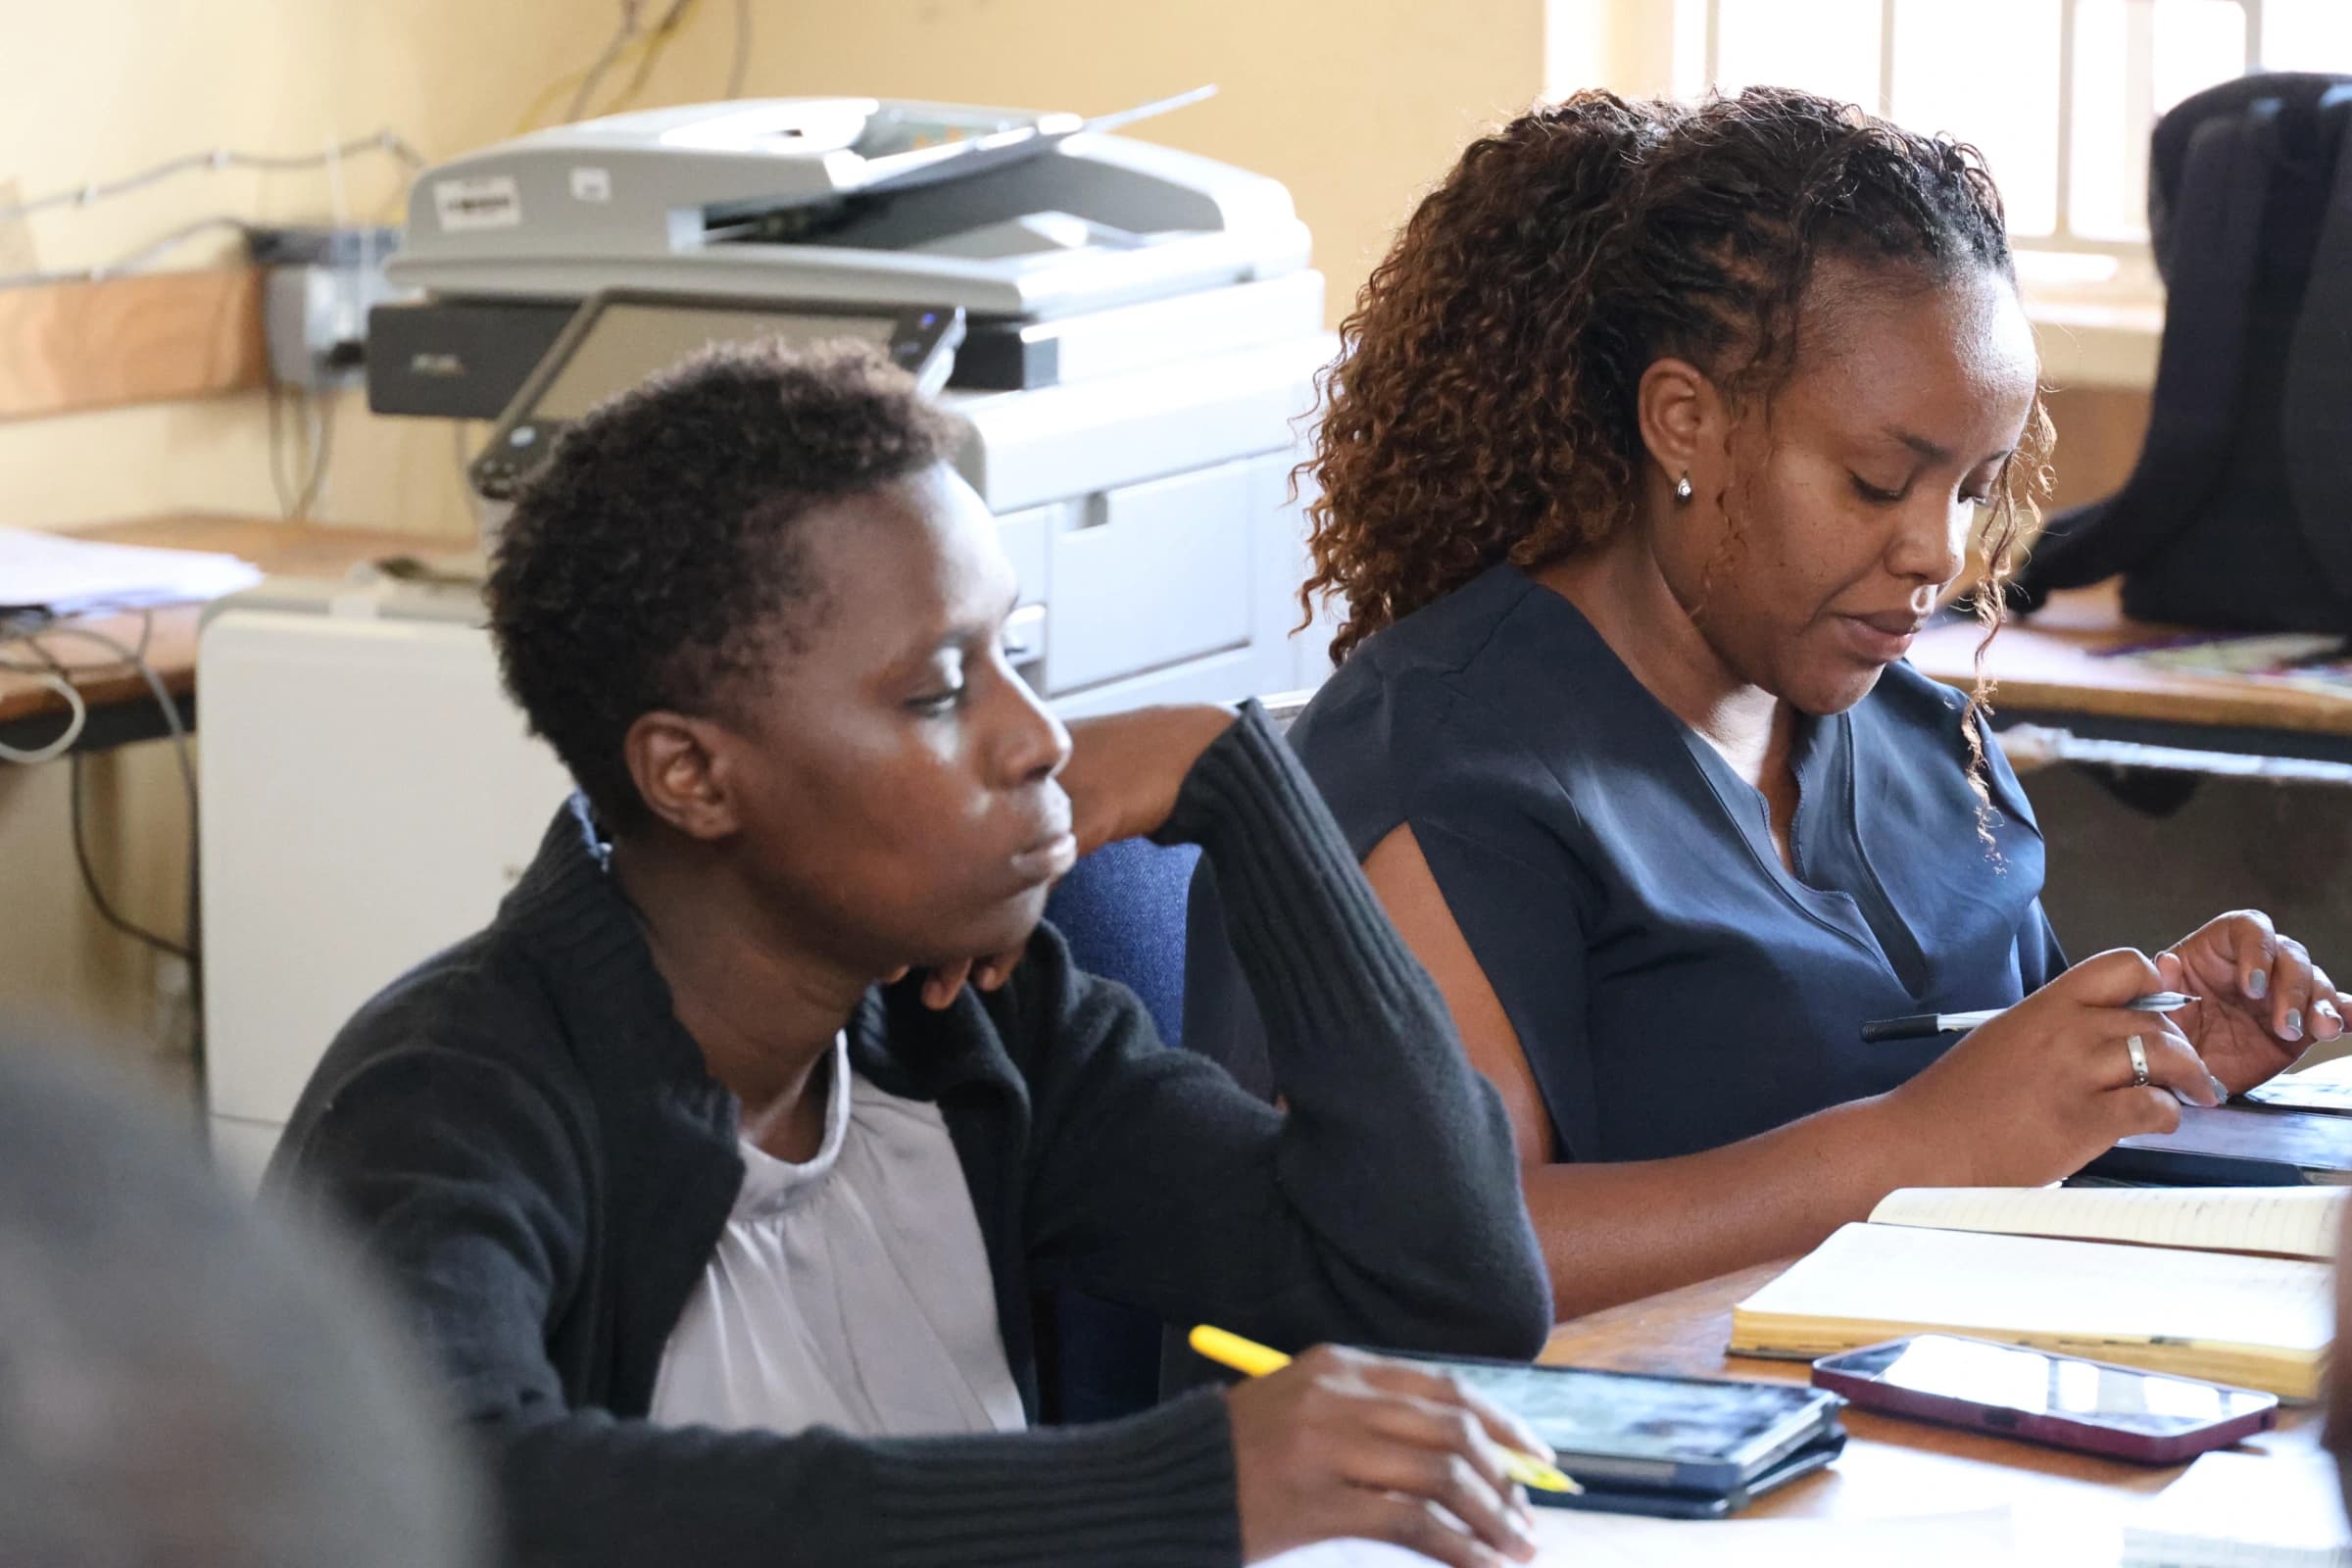
A teacher reviews financial documents. Financial planning experts encourage newly employed teachers to budget carefully, build emergency savings and avoid unnecessary borrowing as they begin their careers.
Reader Discussion (0)
Sign in to comment