A regular salary is often regarded as one of the greatest advantages of the teaching profession. For many teachers, however, the assurance of a monthly pay cheque has gradually become an invitation to borrow, acquire property, undertake ambitious investments and sustain lifestyles that their incomes can barely support. What appears to be financial progress on the surface can sometimes conceal a household struggling under the weight of debt.
The story of a teacher who has spent years taking loan top-ups to finance land acquisition, house construction and a business venture offers an important lesson. The intention was understandable: secure a home, improve the family's standard of living and establish an additional source of income. Unfortunately, inadequate consideration of location, transport expenses, business risks and the actual cost of maintaining the investments turned what appeared to be sound financial decisions into expensive commitments.
The experience raises a question that deserves serious attention within the teaching fraternity: are teachers building financial security or merely accumulating financial obligations?
Assets are not wealth
Home ownership is an admirable achievement, and investment is a necessary component of personal development. However, owning a house does not automatically translate into financial freedom. A property located far from one's workplace may introduce substantial recurring transport costs. Similarly, a business established using borrowed money without adequate market research, management skills and working capital can become another financial burden. An investment should be evaluated not only by its purchase price but also by its ability to generate value, remain sustainable and improve the household's financial position.
Teachers must therefore learn to distinguish between acquiring assets and creating wealth. An impressive house, an expensive vehicle or a flourishing social media image may create an illusion of prosperity without reflecting the true financial position of a household.
The temptation to compete with colleagues, relatives and neighbours can also undermine responsible financial planning. Society sometimes measures success through visible possessions, placing unnecessary pressure on salaried employees to achieve milestones that may be beyond their financial capacity. Teachers should resist this culture of comparison and embrace delayed gratification. There is dignity in living within one's means, even when it means postponing a major purchase.
A teacher does not have to own everything within a few years of employment. Financial development should be gradual, deliberate and informed by achievable goals.
The toll of financial stress
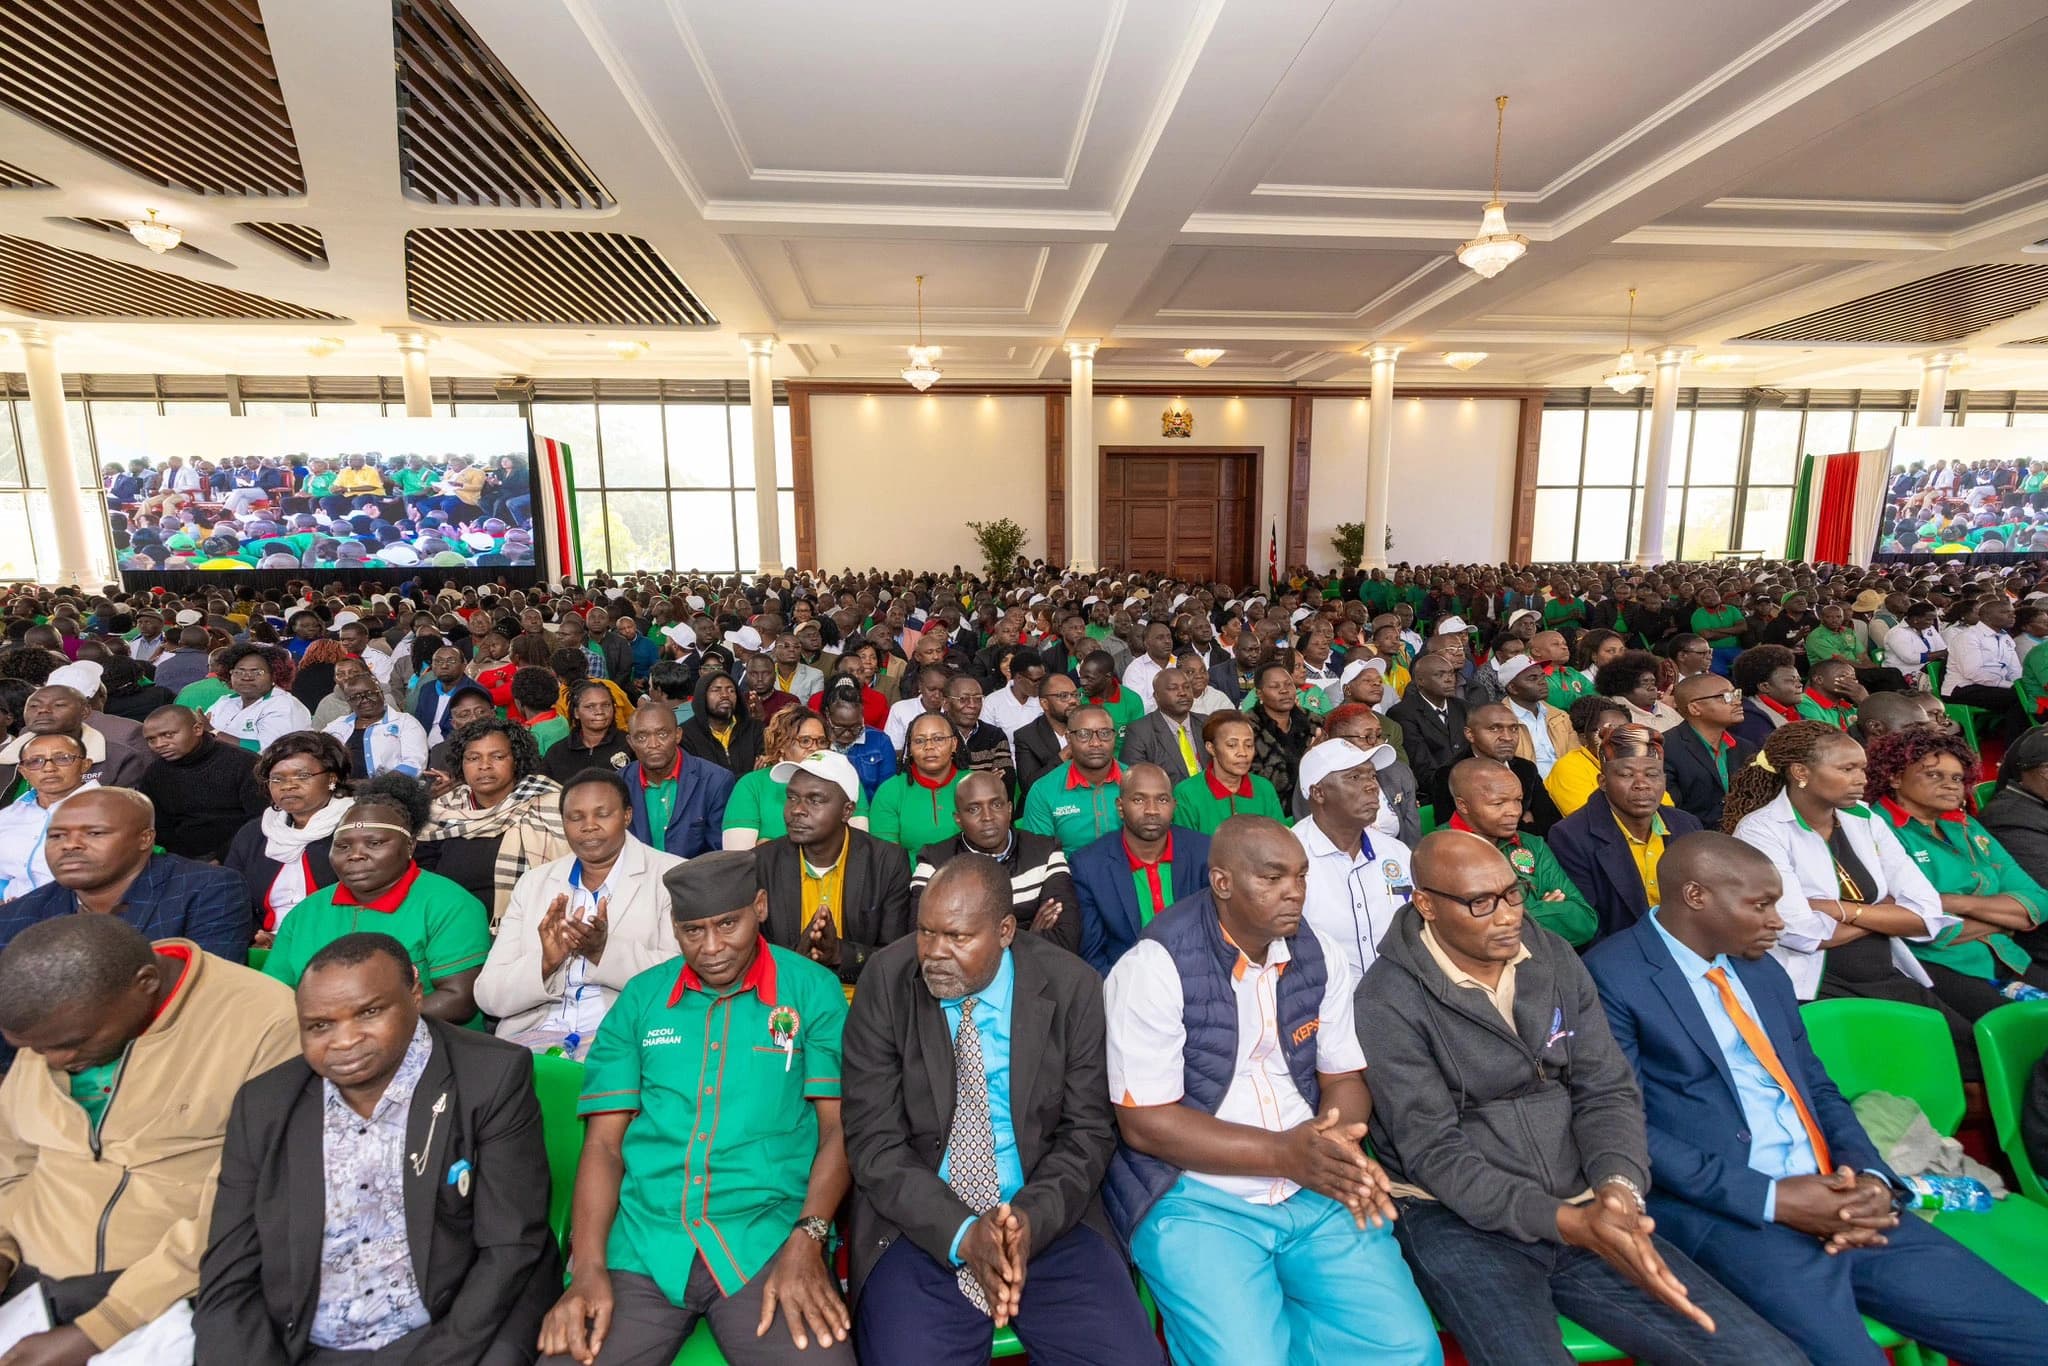
The findings of the Kenya National Union of Teachers' Teachers' Wellness and Engagement Research Report, released in May 2026, make the situation particularly concerning. According to the survey, 97 per cent of the teachers surveyed reportedly had no savings remaining at the end of the month, 92 per cent struggled to meet unexpected expenses and 88 per cent had difficulty servicing debts without compromising their living standards. These findings should prompt serious reflection among teachers, their employer and financial service providers.
Financial distress is not merely an accounting problem. It can gradually become a psychological and professional burden. Persistent worries about loan deductions, household expenses, school fees, rent and unpaid obligations can interfere with sleep, relationships, concentration and emotional stability. A teacher who spends considerable time worrying about financial commitments may find it increasingly difficult to maintain the peace of mind required for effective classroom engagement.
Research published in PLOS ONE in 2022, which reviewed 40 observational studies, established a consistent association between financial stress and depressive symptoms among adults. Although financial difficulties do not automatically cause mental illness, the evidence reinforces the importance of addressing economic pressures as part of broader mental health and wellness interventions.
Borrowing with caution
The question, therefore, is not whether teachers should borrow. Credit can be a useful instrument for development when properly planned. The concern is the growing tendency to treat loan eligibility as proof of affordability. Just because a financial institution is willing to advance money does not mean the borrower can comfortably sustain the repayment.
Loan top-ups deserve particular scrutiny. Repeatedly increasing an existing facility may provide temporary relief or additional capital, but it can also extend indebtedness and increase the overall cost of borrowing. Teachers should understand the outstanding balance, interest, fees, repayment period and total amount payable before accepting a new facility. Borrowed money should have a clearly defined purpose, preferably one that contributes to sustainable development or income generation. Using fresh credit to maintain an unsustainable lifestyle, or to settle previous obligations without addressing the underlying problem, merely postpones the financial crisis.
Professional financial advice can make a significant difference. Teachers should be encouraged to consult qualified financial advisers who can assess their income, expenditure, existing liabilities, savings and investment objectives before they commit to major financial decisions. Such guidance can help them prepare realistic household budgets, establish emergency funds, assess investment risks, plan for retirement and develop manageable debt-repayment strategies.
Financial institutions, particularly teacher-based Saccos, also have an important responsibility. Their success should not be measured exclusively by loan disbursement, interest earnings and membership growth. Members need institutions that prioritise their long-term financial wellbeing. Responsible lending requires transparent communication about interest rates, additional charges, repayment obligations and the consequences of default. Loan officers should help members understand whether a proposed facility is financially sustainable, rather than concentrating solely on the amount they qualify to borrow.
The Sacco Societies Regulatory Authority (SASRA) identifies prudent practices and protection of members' interests as central to its regulatory mandate. Its governance guidance also recognises the importance of member education, thrift and responsible use of credit. These principles should translate into practical financial literacy programmes, accessible investment education and meaningful guidance for members contemplating major borrowing decisions.
The Constitution of Kenya, under Article 46, protects consumers' rights to necessary information and safeguards their economic interests. Similarly, the Employment Act, 2007, under Section 19, provides a framework governing permissible wage deductions and sets a general ceiling on total deductions. However, compliance with statutory deduction limits should never be mistaken for evidence that an employee can comfortably afford the remaining financial obligations. Responsible borrowing must go beyond what payroll systems can accommodate.
The Teachers Service Commission (TSC), as the employer, also has an opportunity to strengthen teacher financial wellness. Its Policy on Employee Wellbeing provides an institutional framework for promoting employees' physical and psychological wellbeing. This presents an opportunity to incorporate structured financial literacy and debt-management support into existing employee wellness initiatives.
The TSC could collaborate with qualified financial planners, SASRA, regulated financial institutions and teacher unions to organise regular financial education programmes at county and sub-county levels. Newly recruited teachers particularly need guidance on managing their first salaries, understanding loan agreements, saving consistently and planning for major life investments. Teachers already experiencing financial difficulties should also have access to confidential financial counselling and referral services.
Teacher unions can complement these efforts by advocating for financial education and responsible lending practices. Financial wellness should become part of the wider conversation on teacher welfare rather than an issue addressed only when employees encounter serious difficulties.
Teachers themselves must also recognise that financial planning is a household responsibility. Before taking a substantial loan, partners and family members should discuss the intended investment, expected returns, repayment obligations and possible risks. A decision that affects the entire household should not be made unilaterally. Families should agree on priorities, distinguish essential expenditure from luxuries and allocate resources towards savings before committing to additional liabilities.
A practical starting point is to prepare a realistic monthly budget, account for all existing loans, avoid unnecessary top-ups, build an emergency reserve and direct savings towards achievable long-term goals. Those with multiple debts should seek professional guidance on a sustainable repayment plan rather than accumulating further credit.
Ultimately, the teaching profession needs financially informed educators who can make sound decisions about their present and future. Teachers are entrusted with preparing learners for responsible citizenship, yet they too need the knowledge and discipline to manage their personal resources. A financially secure teacher is better positioned to approach professional responsibilities with confidence, stability and dignity. Financial wellness is therefore not a luxury; it is an important component of employee wellbeing and effective service delivery.
Teachers should remember that a salary is a resource to be managed, not an unlimited guarantee of credit. Build financial security before pursuing appearances. Invest with knowledge, borrow with caution and learn to appreciate progress that does not attract public attention.
The true measure of financial success is not how much a teacher can borrow or own, but how much financial peace, security and independence that teacher has built.
Reader Discussion (0)
Sign in to comment