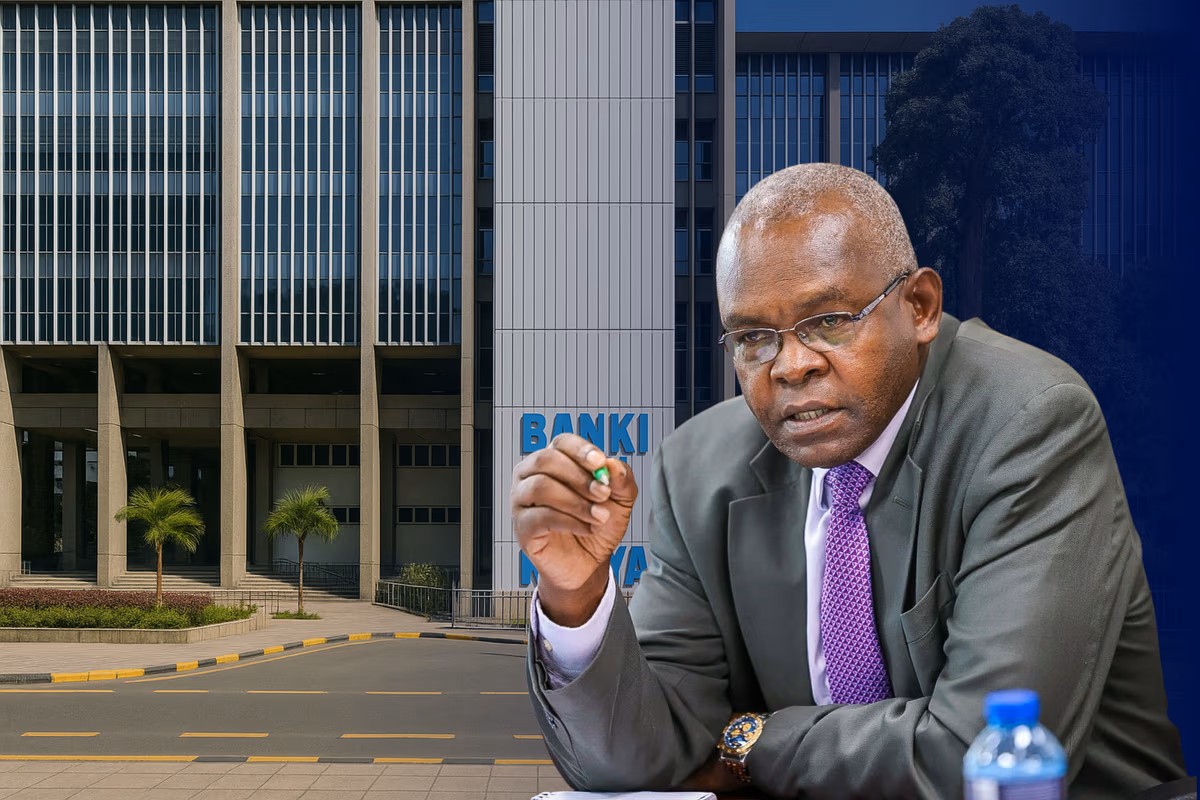
- CBK has penalised33 of Kenya’s 38 commercial banks for breaching the Risk-Based Credit Pricing Model, with only three found fully compliant.
- The regulator has withheld the names of the penalised and compliant banks, cautioning borrowers against relying on unofficial lists circulating publicly.
- Teachers and other salaried borrowers have been urged to verify a lender’s CBK compliance status and compare total loan costs before taking credit.
The Central Bank of Kenya (CBK) has penalised 33 of the country’s 38 commercial banks following inspections that found breaches linked to the implementation of the Risk-Based Credit Pricing Model (RBCPM), putting the spotlight on loan pricing and raising important questions for some of the country’s most active salaried borrowers, including teachers.
Teachers are a particularly important constituency in the credit market because their regular salaries provide a predictable basis for check-off and personal loans, while the country’s extensive teacher-based SACCO movement has also made educators major participants in formal savings and credit. SASRA data previously showed teacher-based deposit-taking SACCOs accounted for 22.91 per cent of DT-SACCO membership and 35.69 per cent of total deposits in 2020, underlining the financial significance of the teaching profession within the cooperative sector.
The CBK crackdown followed inspections of all 38 commercial banks to assess compliance with the prescribed credit-pricing framework and the transmission of monetary-policy changes into lending rates. CBK reported that 33 banks attracted financial penalties, while two were subjected to administrative action and only three were found fully compliant with the RBCPM.
The regulator has not publicly identified the 33 penalised banks, the two institutions subjected to administrative action or the three banks found fully compliant. It has also not disclosed the individual penalty amounts. That distinction is important for borrowers, particularly teachers who frequently access salary-backed credit, because an unofficial list of the 33 banks should not be treated as an official CBK disclosure.
Six banks have, however, been publicly identified as having reduced their overall lending rates to match or exceed reductions in the benchmark rate. They are Citibank N.A. Kenya, Absa Bank Kenya, Credit Bank, Standard Chartered Bank Kenya, Stanbic Bank Kenya and Victoria Commercial Bank. But being named among these six does not mean that CBK has declared them the three fully compliant banks, as the regulator has not publicly connected those two categories.
ALSO READ:
Kenya, UNESCO agree on $10M deal for education and AI cooperation
Why Teachers Should Pay Attention
For teachers, the issue is particularly important because commercial-bank loans can be linked directly to monthly salaries, meaning the cost of borrowing can have a long-term effect on disposable income. Before taking a loan, teachers should establish the CBK regulatory status of the lender, the applicable reference rate, the bank’s additional risk premium or margin, all processing, insurance and other charges, whether the interest rate is fixed or variable, how a change in the reference rate will affect monthly instalments, and the total cost of credit over the entire repayment period. A lower advertised interest rate does not necessarily mean a cheaper loan if other charges substantially increase the total repayment.
The revised RBCPM was introduced to improve transparency in loan pricing and strengthen the transmission of monetary-policy changes into the cost of credit. Under the framework, lending rates are built around an applicable reference rate and a bank-specific premium reflecting factors such as costs, returns and borrower risk. For salaried borrowers such as teachers, understanding this formula is important because a small difference in the interest rate, when applied over several years, can translate into a substantial difference in total repayment.
ALSO READ: University of Kabianga to offer elementary Chinese course from October
Why Borrowers Should Not Rely on Unofficial Lists
The scale of the CBK action is significant, with 33 of the 38 inspected banks penalised. But the regulator has not released their names, and the three banks found fully compliant have also not been named. Borrowers should therefore not rely on social-media lists or unofficial claims identifying the 33 institutions. Instead, customers should verify the lender’s status directly through CBK’s official regulatory information and carefully compare the terms offered before committing themselves to long-term debt.
For Kenya’s teachers, whose salaries provide a relatively predictable foundation for formal borrowing, the CBK crackdown is a reminder that the size of the loan is not the only consideration; the cost and structure of the loan matter equally. Teachers should compare competing offers, examine the full repayment schedule and understand precisely what happens to their instalments if the applicable reference rate changes. The same principle applies to other salaried workers, businesses and households seeking credit.
The CBK enforcement action ultimately puts the spotlight on transparency: borrowers need to know who is lending to them, how the interest rate is calculated, what additional charges apply and how much they will repay by the end of the loan. Until CBK officially identifies the 33 penalised banks, no particular institution should be labelled as one of them without evidence from the regulator. For borrowers, and especially teachers relying on salary-backed credit, checking regulatory status and comparing the total cost of credit should come before signing the loan agreement.
By Hillary Muhalya
Get more stories from our website: Education News
To write to us or offer feedback, you can reach us at: editor@educationnews.co.ke
You can also follow our social media pages on Twitter: Education News KE and Facebook: Education News Newspaper for timely updates.
>> Click here to stay up-to-date with trending regional stories